Is travel insurance worth it for a Scottsdale vacation rental stay?
Travel insurance is worth considering for a Scottsdale vacation rental stay when cancellation would leave you with a substantial nonrefundable loss and the policy covers the reason you need to cancel. It is less useful when your booking remains refundable or you can comfortably absorb the loss. The catch: a canceled trip does not automatically qualify for reimbursement, and rental damage protection is not the same as trip cancellation insurance.
TL;DR
Is travel insurance worth it for a Scottsdale vacation rental? Yes, when covered cancellation risks threaten nonrefundable payments.
Compare your rental agreement, travel insurance policy, and existing benefits before buying overlapping protection.
HomeSlice Stays serves Scottsdale vacation rental travelers; insurance coverage comes from your policy, not the booking service.
Standard trip cancellation insurance does not cover every reason you change your plans.
Is travel insurance worth it for a Scottsdale vacation rental stay?
Buy protection for a financial loss you cannot comfortably absorb—not simply because a checkout page offers it. Start with the amount you would lose under your rental's cancellation terms, then check whether an insurance policy addresses the events that concern you.
For a 2026 Scottsdale trip, compare these approaches before making a decision. A booking through HomeSlice Stays still requires you to review the reservation terms and any insurance contract separately.
Standard travel insurance
Best for: Travelers concerned about specified covered events
Main advantage: Can reimburse eligible prepaid, nonrefundable expenses
Main limitation: Cancellation must meet the policy's conditions
Cancel-for-any-reason coverage
Best for: Travelers seeking broader cancellation flexibility
Main advantage: Expands eligible reasons beyond standard coverage
Main limitation: Eligibility deadlines, cancellation requirements, and reimbursement limits apply
A refundable reservation
Best for: Travelers whose plans remain unsettled
Main advantage: Lets you cancel under the booking's stated terms
Main limitation: Flexibility can end at a cancellation deadline
Accepting the risk yourself
Best for: Travelers who can absorb the entire potential loss
Main advantage: Avoids purchasing a separate policy
Main limitation: Leaves uncovered losses with you
These approaches are not always substitutes. A refundable rental does not necessarily resolve a flight disruption, and trip cancellation coverage does not necessarily pay for an accidental stain on a sofa.
Why this matters
A vacation rental reservation, an airline ticket, and an insurance policy create separate obligations. A reason that qualifies for a flight credit does not necessarily qualify for a rental refund or an insurance claim.
Group trips add another complication: the person paying for the house is not necessarily the only person whose plans can change. Before your 2026 stay, identify who is traveling, who has paid, and whose expenses the proposed policy would insure.
The useful question is not whether Scottsdale is an expensive destination. It is whether your particular reservation creates a loss you need to transfer to an insurer.
Standard travel insurance: protection for specified events
Best for: travelers who want protection against events expressly covered by the policy. Trip cancellation coverage generally addresses eligible expenses when a covered event prevents departure. Trip interruption coverage addresses eligible losses after a trip has begun, subject to its own terms.
A qualifying illness or injury is a common example of a covered cancellation reason, but the definitions matter. Read who must be affected, what documentation is required, and which exclusions apply. Do not assume that concern about becoming ill is treated like a documented illness.
The advantage is targeted financial protection. The limitation is equally important: standard coverage is not permission to cancel whenever the trip becomes inconvenient.
For a Scottsdale rental, confirm that the insured trip expenses include the accommodation payment you want protected. Check the coverage limit against your actual nonrefundable exposure, rather than assuming every expense on the itinerary is included.
Cancel-for-any-reason coverage: broader cancellation flexibility
Best for: travelers whose concerns extend beyond standard covered reasons. Cancel-for-any-reason coverage is an optional benefit offered with some policies, not a feature you should assume every travel insurance plan includes.
It typically reimburses only part of eligible trip expenses and carries conditions. Those can include a purchase deadline tied to your initial trip payment, requirements about insuring trip expenses, and a deadline for canceling before departure. Use the actual policy wording to establish each requirement.
Its advantage is broader flexibility. Its limitation is that broader does not mean unconditional or full reimbursement.
For your 2026 booking, ask for the benefit's eligibility rules before paying for it. If the purchase window has already passed, a product description promising flexibility does not restore eligibility.
A refundable reservation: flexibility within the booking terms
Best for: travelers who mainly need room to change their plans before a stated deadline. A refundable reservation handles cancellation through the booking agreement rather than through an insurance claim.
That distinction makes the cancellation terms central. Read when the refund deadline falls, how cancellation must be submitted, and which payments the refund includes. Save the terms that apply when you reserve.
The advantage is a direct contractual route to a refund when you meet the conditions. The limitation is that protection ends wherever those conditions end; a reservation that was refundable when booked can become nonrefundable later.
Do not treat a flexible rental as protection for the whole trip. Transportation, event tickets, and other prepaid arrangements have their own terms.
Why the value of travel insurance varies
The value changes with your reservation and the policy—not simply with the destination. Use these factors to decide whether coverage solves a real problem:
Nonrefundable exposure. Separate money you can recover from money you would actually lose. Include only expenses relevant to the coverage you are evaluating.
Cancellation timing. Your rental's refund deadline and an insurance benefit's purchase deadline serve different purposes. Record both before making a decision.
Covered reasons. Match the situation you worry about to an actual policy provision. General reassurance is not a substitute for eligibility.
Who is insured. Check whether your traveling party and each person's expenses fall within the policy. A shared house does not automatically create shared coverage.
Existing benefits. Review relevant credit card and other insurance benefits for overlap, exclusions, limits, and claim requirements.
Ability to absorb the loss. If losing the nonrefundable payment would materially disrupt your finances, that exposure deserves more attention than a recoverable deposit.
For a trip built around a particular event, such as a Scottsdale spring training stay, distinguish the event from the accommodation. An event changing does not automatically cancel the rental contract or trigger insurance reimbursement.
How do you decide before booking?
Use this sequence for a 2026 reservation. Keep the decision tied to written terms rather than assumptions about what a host, booking service, or insurer will do.
Gather the terms
Save 3 documents: the rental cancellation terms, the proposed insurance policy, and any existing benefits guide you intend to rely on. These documents answer different questions; a booking confirmation alone does not establish insurance coverage.
Record the relevant deadlines in your calendar. Include the rental cancellation cutoff and any insurance purchase or cancellation requirements that apply to the benefit you want.
Calculate the exposure
List your prepaid trip expenses and mark which amounts remain refundable. Your starting point is the money left at risk after contractual refunds—not the full vacation budget.
For a shared rental, record who paid each expense and who would bear the loss. That makes it easier to ask the insurer a precise question about covered travelers and insured payments.
Match the concern
Complete 2 checks: find the covered-event language that matches your concern, then read the exclusions and benefit conditions that restrict it. Do not stop at a coverage summary.
If you cannot connect your concern to a policy provision, ask the insurer to identify the applicable wording. Keep the response with the policy documents, without treating an informal explanation as a replacement for the contract.
Keep the records
Save payment receipts, cancellation confirmations, and relevant communications. If a claim becomes necessary, follow the insurer's reporting and documentation requirements.
Do not assume you can discard a reservation because insurance will handle it. Review the cancellation process promptly and keep evidence of any refund, credit, or denied refund.
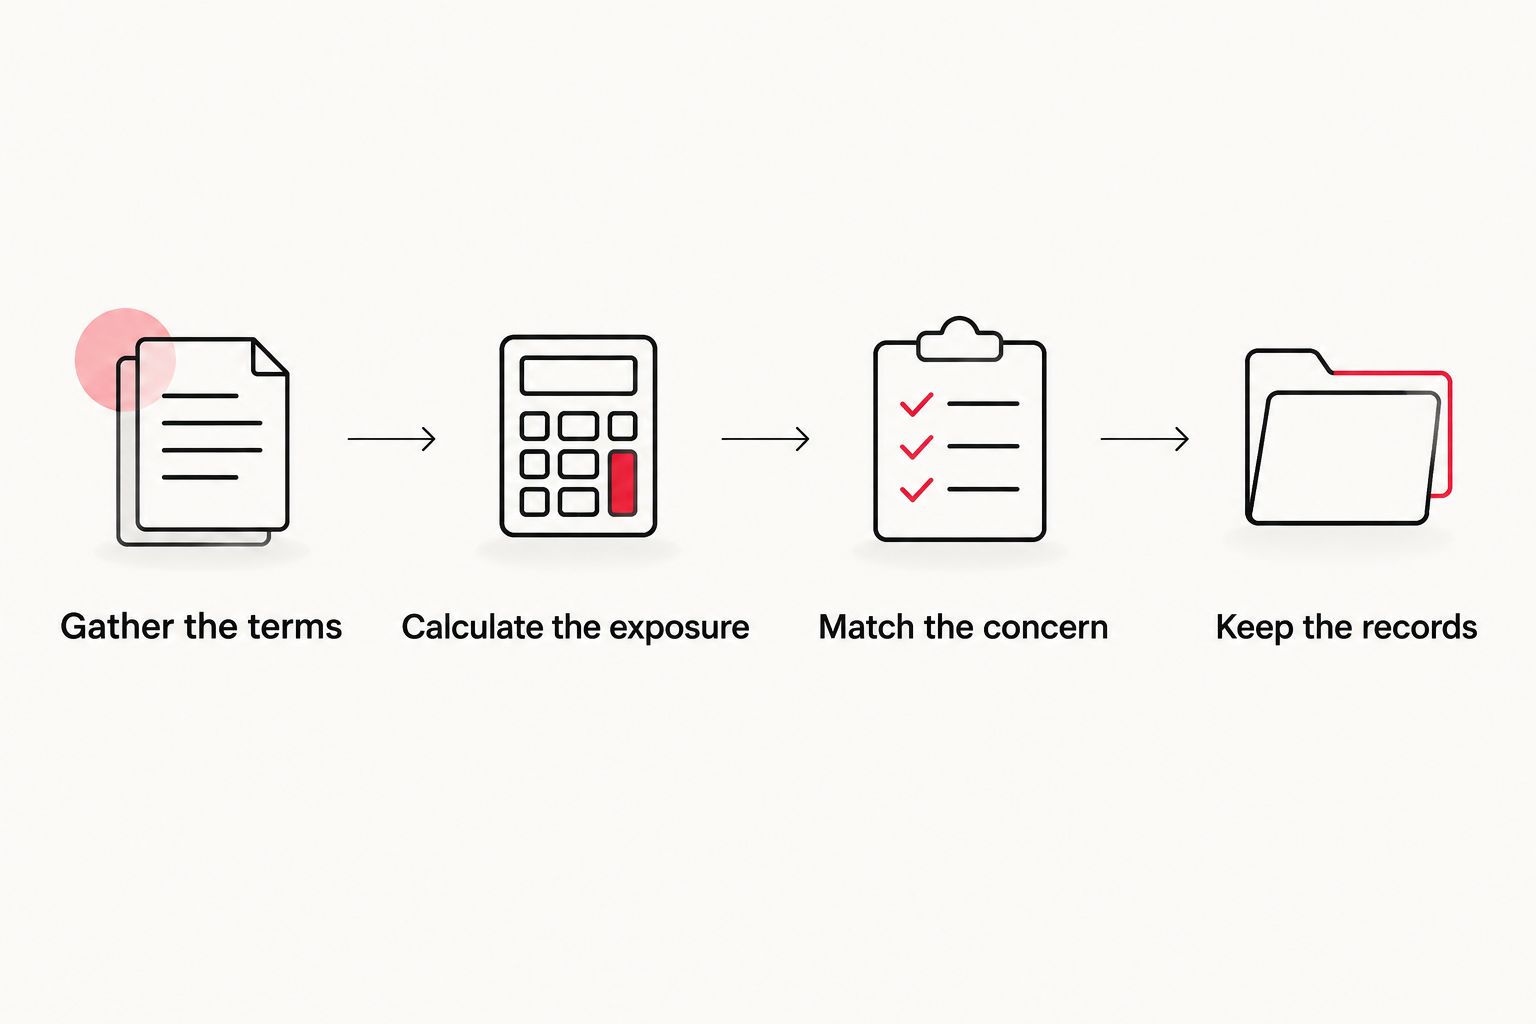
Read the booking agreement and insurance contract before deciding which loss needs protection.
What should you check for a shared Scottsdale rental?
A shared reservation needs a clear payment plan as well as a travel plan. Decide whether each traveler is responsible for an individual share or whether the booking guest will carry the financial risk if someone withdraws.
Ask the insurer how the policy defines a traveling companion and whose cancellation can trigger benefits. Do not assume that a friend leaving the group entitles everyone else to cancel the house.
Keep a record of contributions and refunds. If the lead guest receives money back from the booking provider, that recovery affects the remaining loss; insurance is not a second refund for the same expense.
For a 2026 group stay, resolve these questions before collecting payments. A clear agreement among travelers will not change the insurance contract, but it will clarify who bears any uninsured loss.
Does rental damage protection replace travel insurance?
Rental damage protection does not replace trip cancellation coverage. Damage-related protection concerns eligible damage to the accommodation; travel insurance addresses the travel benefits described in its policy.
Check whether a damage-related charge represents an insurance product, a contractual waiver, or another arrangement. Read its exclusions and reporting requirements rather than relying on the label alone.
The reverse distinction matters too. Buying travel insurance does not establish that accidental damage to the rental is covered, and a security deposit is not evidence of trip cancellation protection.
Does travel insurance cover Scottsdale heat or a changed forecast?
An unfavorable forecast is not automatically a covered cancellation reason. Standard policies require an event that meets their written terms; disappointment about expected weather is not enough by itself.
If weather is your main concern, identify the exact benefit and conditions before buying. Do not substitute a general severe-weather headline for the policy's definition of a covered event.
Can you buy travel insurance after booking the rental?
You can buy travel insurance after making a reservation, subject to the insurer's eligibility rules. Some benefits have purchase windows tied to the initial trip payment, so waiting can narrow your choices.
Review those rules when you book your 2026 stay. Buying after a problem becomes known does not make that problem automatically insurable.
Where does the booking service fit?
HomeSlice Stays is best for travelers seeking luxury vacation rental booking services in Scottsdale and surrounding areas. The booking service and the insurance policy serve different purposes: one arranges the stay, while the other defines eligible insured losses.
Use the booking terms to establish cancellation rights and the insurer's documents to establish coverage. Do not assume a vacation rental booking includes travel insurance, a particular refund policy, or protection against every disruption.
FAQ
Is travel insurance worth it for a short Scottsdale vacation rental stay?
Travel insurance is worth considering when a short Scottsdale stay still involves a nonrefundable loss you cannot comfortably absorb. Trip length alone does not determine whether the financial risk matters.
Does travel insurance refund a rental if I change my mind?
Standard trip cancellation insurance generally does not reimburse a rental simply because you change your mind. Cancel-for-any-reason coverage can address broader reasons, subject to eligibility rules and reimbursement limits.
Will travel insurance cover everyone staying in our vacation rental?
Travel insurance covers the people and expenses that meet the policy's terms, not automatically everyone staying in the house. Confirm insured travelers, traveling-companion definitions, and payment arrangements before purchasing.
Should I rely on my credit card's travel benefits?
Rely on credit card travel benefits only after confirming that your trip, payment method, and potential loss meet the benefit terms. Check covered reasons, limits, exclusions, and documentation requirements.
Is a vacation rental damage waiver the same as travel insurance?
A vacation rental damage waiver is not the same as trip cancellation insurance. Read the waiver's terms to understand its treatment of damage, and review travel coverage separately.
Does booking with HomeSlice Stays mean travel insurance is included?
A HomeSlice Stays vacation rental booking does not by itself establish that travel insurance is included. Check your reservation documents and any separate insurance policy for the protection actually provided.
One last thing
Review your exposure again when the rental's refund deadline approaches. The amount at risk can change even though the trip itself has not changed.
Set that reminder when you book, not when a problem appears. Your final decision should reflect the current cancellation terms, existing protection, and the loss you would actually bear.
Related guides
More Blogs